Canada's Budget 2026: Who Benefits and What It Means for Your Money
Last updated:
This article is general information, not financial advice. Rates, limits and offers change, so confirm current details with the source or a licensed professional. Read the full disclaimer.
Canada's federal Budget 2026, tabled on November 5, 2026 by Finance Minister François-Philippe Champagne, aims most of its household help at people with low and modest incomes: a one-time top-up to the Canada Groceries and Essentials Benefit in early 2027, a bigger benefit for low-wage workers, and a caregiver credit that would pay out even when no tax is owed. For business owners, the main changes are a large deduction for new business investment, a capital gains exemption of up to $15 million for qualifying investments in growing companies, and simpler tax instalments for the self-employed.
This guide sorts the measures by who they help, so you can go straight to the parts that apply to you. Almost everything below is a proposal: tax and benefit changes only take effect once Parliament passes the laws that carry them, and details can change along the way. Dates are the ones the budget gives, as of November 2026.
Quick answer: who benefits
- Individuals and families: a one-time grocery and essentials supplement in early 2027 (up to $339 single, up to $679 for a couple with two children), fuel tax relief into early 2027, a single May 15 tax deadline from 2027 returns, and flat amounts instead of receipts for some claims.
- Workers: the Build Canada Workers Benefit pays more and starts at $500 of earnings instead of $3,000, from the 2027 tax year. Tradespeople, commission employees and employed artists also get easier deductions.
- Caregivers: the Canada Caregiver Credit becomes refundable, worth up to $1,260 a year from 2027.
- Home buyers: more mortgage rate information, a $1.5 million price limit for optional mortgage insurance, and new insurance rules for three- and four-unit homes from February 1, 2027.
- Retirees and savers: a planned "RRSP for life" with no forced RRIF conversion at 71, and Canada Strong Notes, a new principal-protected investment planned for early 2027.
- Self-employed and small business owners: one May 15 date to file and pay, a higher instalment threshold ($7,500) and an option for one annual instalment from 2028, and the Canada Growth Incentive for people who invest in growing companies.
- Larger businesses: the Productivity Mega Deduction for new investment and an expanded SR&ED research credit.
Budget 2026 at a glance, by who it helps
| Who it helps | Measure | What changes | When (as proposed) |
|---|---|---|---|
| Individuals and families | 2027 Canada Groceries and Essentials Benefit Supplement | One-time 50% increase for the 2026-27 benefit year | Early 2027 |
| Individuals and families | Fuel excise tax relief | Federal fuel excise tax suspension extended | Into early 2027 |
| Individuals and families | Tax filing date | One date to file and pay: May 15 | 2027 tax returns, filed in 2028 |
| Workers | Build Canada Workers Benefit | Lower earnings threshold, higher maximum, advance payments phased out | 2027 tax year |
| Caregivers | Refundable Canada Caregiver Credit | Up to $1,260 a year, even with no tax owing | 2027 tax year |
| Home buyers | Optional mortgage insurance | Price limit from $1 million to $1.5 million | Once regulations are in place |
| Home buyers and builders | "Missing middle" mortgage insurance | New flexibility for three- and four-unit homes | February 1, 2027 |
| Retirees and savers | RRSP for life | No forced RRSP to RRIF conversion at 71 | Under consultation |
| Savers and investors | Canada Strong Notes | Principal-protected notes linked to the Canada Strong Fund | Planned for early 2027 |
| Self-employed | Tax instalments | Threshold from $3,000 to $7,500, single annual instalment option | Taxation years from 2028 |
| Investors in growing companies | Canada Growth Incentive | Capital gains exemption on up to $15 million from eligible investments | Shares in eligible companies (see details) |
| Businesses | Productivity Mega Deduction | Lower tax rate on new business investment | Business investment going forward |
For individuals and families
More help with groceries and everyday costs
The Canada Groceries and Essentials Benefit (the former GST/HST credit) is paid every quarter to more than 12 million people with low or modest incomes. It already got a one-time 50% top-up in June 2026 and a 25% increase for five years starting in July 2026.
Budget 2026 proposes one more boost: the 2027 Canada Groceries and Essentials Benefit Supplement, a one-time 50% increase for the 2026-27 benefit year, delivered in early 2027.
| Household | Supplement (up to) | Total support for 2026-27 (up to about) |
|---|---|---|
| Single person, no children | $339 | $1,290 |
| Couple with two children | $679 | $2,570 |
The benefit is based on your tax return, so filing on time is what keeps these payments coming. You can check payment dates on the CRA benefit payment dates page.
Fuel, energy and family outings
- Fuel: the temporary suspension of the federal fuel excise tax on gasoline and diesel, in place since April 20, 2026, is extended into early 2027.
- Heat pumps: a National Heat Pump Rebate Program for up to 820,000 households, with more help for lower-income households.
- Museums: national museums become permanently free for children and youth under 25.
Tax season: May 15 and fewer receipts
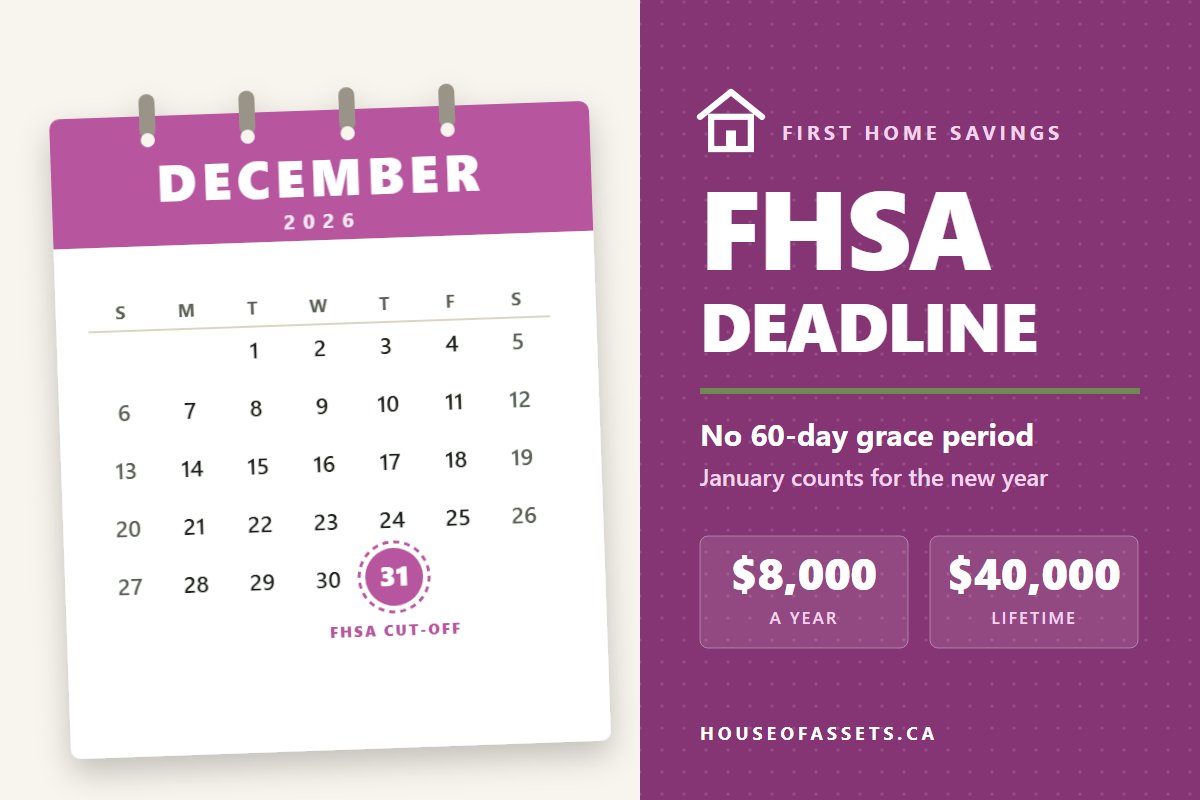
Today most people must file and pay by April 30. Budget 2026 proposes one date, May 15, to file and pay for everyone, starting with 2027 tax returns. Your 2026 return, filed in spring 2027, keeps the current dates.
The budget also offers optional flat amounts instead of tracking receipts for some claims, starting with the 2027 tax year, including a flat $1,000 for the moving expense deduction, $1,000 (once) for the home accessibility tax credit and $1,200 per child for the adoption expense tax credit. You could still claim actual costs with receipts.
Credit cards and payday loans
- Credit cards: when a card carries balances at different rates (for example, purchases and a cash advance), the government intends to consult on requiring any payment above the minimum to go to the highest-rate balance first, as Québec already requires.
- Payday loans: the government intends to change the Criminal Code rules so payday loans must allow at least 42 days to repay, in instalments, with no credit insurance charges.
For workers
Build Canada Workers Benefit
The Canada Workers Benefit is a refundable tax credit that tops up the pay of about 3 million low- and modest-income workers. Budget 2026 proposes to rename and expand it as the Build Canada Workers Benefit, starting with the 2027 tax year:
| Current Canada Workers Benefit | Proposed Build Canada Workers Benefit | |
|---|---|---|
| Minimum working income | $3,000 | $500 |
| Minimum for the disability supplement | $1,150 | $200 |
| Maximum, single with no children | $1,709 | $1,859 |
| Maximum, families | $2,943 | $3,143 |
The budget estimates about 1.9 million workers would get more, including 180,000 people who get nothing today.
The timing of payments also changes. Advance payments would be cut in half for the 2027 tax year (starting July 2027) and stop from the 2028 tax year. After that, the full benefit would arrive once you file your return. If you count on the advance payments today, that money would come later, in one amount, after tax time.
Easier deductions for some jobs (2027 tax year)
- Tradespeople and apprentices in construction who relocate temporarily for work could deduct a flat $1,500 a year instead of tracking actual costs.
- Commission employees could claim travel and vehicle expenses under the general employee rules and still claim other expenses against commission income.
- Employed artists could deduct expenses up to their employment income from artistic work, replacing the current cap.
- Volunteer firefighters and search and rescue volunteers would get one combined credit, with hours from both kinds of service counting toward the 200-hour requirement.
For caregivers and people with disabilities
The Canada Caregiver Credit helps people who support a spouse, partner or dependant with a physical or mental impairment. It is currently non-refundable, so it can only reduce tax you owe, and a caregiver with little or no income tax gets little or nothing from it.
Budget 2026 proposes to make it fully refundable from the 2027 tax year. Eligible caregivers would receive up to $1,260 a year (the 2027 amount, indexed after that) whether or not they owe tax. The budget estimates 585,000 caregivers would get support, including 180,000 who receive no benefit from the credit today.
The medical expense tax credit would also get simpler, with optional flat amounts for some costs (such as gluten-free food for people with celiac disease) and fewer prescription requirements for certain items.
For home buyers and homeowners
- Rate transparency: new regulations so the Bank of Canada publishes more information on insured mortgage rates, making it easier to compare offers.
- Income checks through the CRA: the CRA could confirm a borrower's income directly with lenders and mortgage insurers, aimed at a faster application and less mortgage fraud. A pilot is funded over three years starting in 2027-28.
- Optional mortgage insurance: the home price limit rises from $1 million to $1.5 million, with 30-year amortizations allowed when at least one borrower is a first-time buyer or the home is newly built.
- Prepayment penalties: the government plans to consult on making early payoff penalties on insured mortgages easier to understand and compare.
- "Missing middle" homes: new mortgage insurance flexibility for three- and four-unit homes, and private insurers allowed to insure five- to fifty-unit properties, starting February 1, 2027.
For retirees, savers and investors
RRSP for life
Today you must convert your RRSP into a RRIF (or buy an annuity) by the end of the year you turn 71, and a RRIF comes with yearly minimum withdrawals. Budget 2026 announces the intention to merge the main features of both into a single "RRSP for life", so there would be no conversion step at 71. People over 71 would still have to take minimum withdrawals each year. This is at an early stage: the government is asking Canadians for written comments before it drafts the rules.
Canada Strong Notes
Canada Strong Notes would let Canadians invest in the $25 billion Canada Strong Fund. According to the government's technical backgrounder, the notes would have set terms (such as five, seven or ten years), a base interest rate, protection of your original investment at maturity, and extra returns linked to how the fund performs. The government is working with financial institutions on how they would be sold and redeemed, aiming for a launch in early 2027.
Rates, fees, early redemption rules and whether the notes can be held in a TFSA or RRSP have not been published yet. As with any investment, read the product terms in full once they are released.
Foreign property reporting
If you hold investments outside Canada, the threshold for filing Form T1135 would double from $100,000 to $200,000 of foreign property, and simplified reporting would apply below $500,000, for years ending after 2026.
For the self-employed and small business owners
One tax date and simpler instalments
- Filing and paying: self-employed people and their spouses or partners now file by June 15 but must pay by April 30. Under the proposal, both would be due on May 15, starting with 2027 tax returns.
- Instalment threshold: quarterly tax instalments are now required when net tax owing is over $3,000 ($1,800 in Québec). Budget 2026 proposes $7,500 ($4,500 in Québec), indexed to inflation, for taxation years starting on or after January 1, 2028.
- One instalment a year: people whose main income is from a business (including professional or commission income) could make a single annual instalment instead of four quarterly ones.
Canada Growth Incentive
The Canada Growth Incentive is aimed at people who invest in high-potential Canadian companies:
- a new tax exemption on up to $15 million in capital gains from eligible investments;
- an enhanced small business rollover, which defers tax on a gain when the money goes into new eligible small business shares, with a longer window to reinvest and a looser asset test, for sales on or after January 1, 2027.
The eligibility rules for both are detailed and technical, so the tax measures document and a tax professional are the places to confirm whether a specific investment would qualify.
For larger businesses
- Productivity Mega Deduction: faster write-offs for new business investment, which the budget says lowers the marginal effective tax rate on new business investment from 13% to 6.4%.
- SR&ED expansion: $930 million to extend the Scientific Research and Experimental Development tax incentives to some commercialisation expenses.
- Energy and resources: more than $50 billion toward doubling electricity grid capacity by 2050, $2.3 billion for critical minerals and $6.5 billion over six years for the forest sector.
- Canada Strong Fund: a $25 billion fund to invest in major Canadian projects, which the Canada Strong Notes above would let individuals invest in.
What happens next
A budget is a plan. Each measure needs legislation or new regulations, and the CRA will post forms and guidance as changes become law. For the official documents, see the Budget 2026 home page, the Budget 2026 key measures, Chapter 3: A more affordable life and the tax measures supplementary information.
For more on building a safety net while these changes roll out, see our guides on how to structure an emergency fund, GIC vs high-interest savings account for an emergency fund and resources for low-income seniors, plus our list of other financial resources.
Sources
- Department of Finance Canada, Budget 2026: Masters of our destiny, November 5, 2026
- Department of Finance Canada, Budget 2026: Key Measures
- Budget 2026, Chapter 3: A more affordable life
- Budget 2026, Tax measures: Supplementary information
- Budget 2026, Canada Strong Fund technical backgrounder (PDF)
Cover image: photos of Mark Carney by Bryan Berlin (CC BY-SA 4.0, source) and François-Philippe Champagne by Reinis Inkēns, Saeimas Administrācija (CC BY-SA 2.0, source), via Wikimedia Commons. The cover image is shared under CC BY-SA 4.0. House Of Assets is not affiliated with or endorsed by the Government of Canada.